
Key Takeaways
- StaySTRA data shows Santa Barbara averaging $9,549 per month in August 2026 with occupancy holding nearly flat year-over-year, making it one of the strongest Q3 performers in the dataset.
- Austin, TX posted a 3.5-percentage-point occupancy gain year-over-year in Q3 2026, the only major urban market in the StaySTRA dataset to show positive occupancy growth during the quarter.
- Mountain resort markets (Breckenridge, Park City) showed summer occupancy softness, as expected in ski destinations. Park City’s 9.5% ADR growth signals pricing confidence heading into ski season.
- The dominant Q3 pattern: premium markets held ADR even as occupancy softened, while high-supply coastal markets saw occupancy fall without enough rate growth to compensate.
- Supply growth across major STR markets has stalled. Established operators entering Q4 face less competition for bookings than they did a year ago.
Santa Barbara short-term rental operators averaged $9,549 per month in August 2026 while holding occupancy at 67.1%, virtually unchanged from a year earlier. Think of that for a moment: in a summer when many markets were wrestling with softening demand, one of California’s premium coastal markets delivered near-record revenue on nearly unchanged occupancy, simply because rates moved in the right direction. The Q3 2026 data that StaySTRA has compiled through August tells a story that is more nuanced than any single headline, and that nuance is exactly where the investment signal lives.
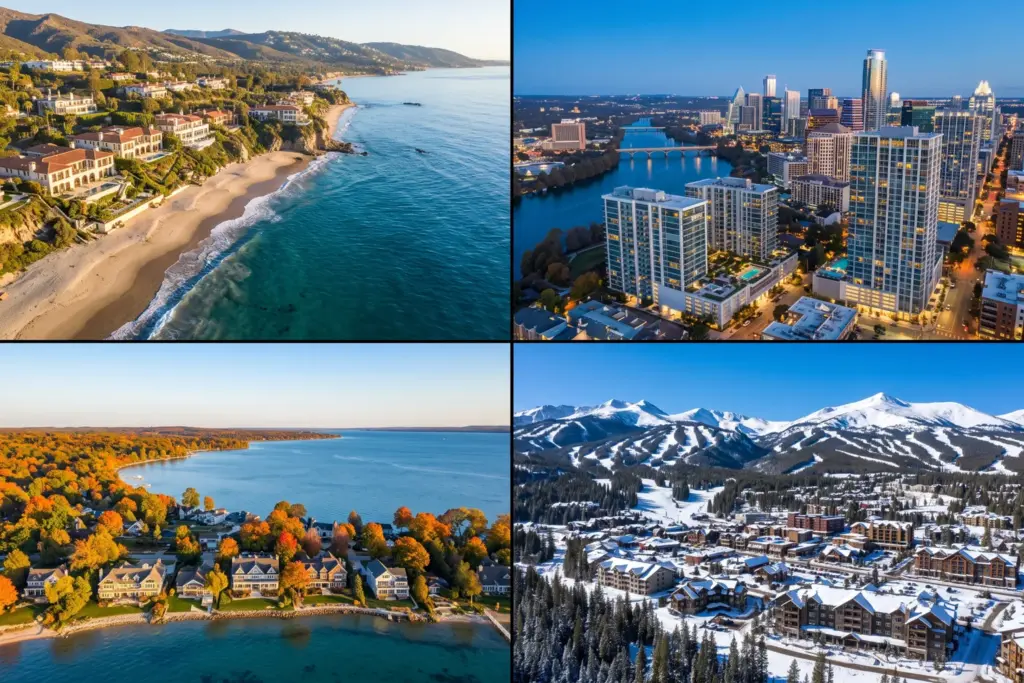
I have been reading market performance data for forty years, first as a government statistician in Washington and now, from a desk with a good view of the Sangre de Cristo Mountains and a cup of black coffee, as a market researcher. A quarter’s worth of numbers rarely tells one story across all market types. Q3 2026 is no exception. Urban markets diverged. Coastal markets separated by quality tier. Mountain resort destinations posted summer occupancy declines while their operators either held pricing power or did not, and the difference matters heading into ski season. What makes Q3 2026 interesting for investors is the signal embedded in that divergence, and what it means for where you want to be positioned entering Q4.
A note on the data: StaySTRA’s market metrics are compiled through August 2026. September data is being finalized as part of the normal processing cycle. The figures in this article reflect Q3 performance as available through the close of August. The directional signals they show are consistent with what historical patterns suggest for September across these market types. Year-over-year changes in this article compare August 2026 against August 2025 from the StaySTRA database.
The National Picture for Q3 2026
Industry data from AirDNA’s midyear 2026 report projects national STR occupancy averaging around 57.4% for 2026, edging above the pre-pandemic benchmark of approximately 57.0% (AirDNA). That is meaningful context for reading the individual market numbers below: the broad picture is positive, not neutral. AirDNA projected national RevPAR to grow approximately 2.9% for the year, and supply growth has slowed relative to the pace seen in 2023 and 2024.
That supply picture matters more than it might appear. When fewer new listings enter a market, existing operators compete against each other less aggressively for the same demand pool. The operators who are still standing after the past two years of market correction have built toward quality, and they are reaping the benefit. If you own an established listing in a market with tightening supply, Q3 2026 data suggests the structural conditions are more favorable than the occupancy headlines alone would imply.
Stay with me on this supply point, because it is the part of the Q3 story that most market summaries skim past. The StaySTRA Analyzer breaks this down market by market if you want to see where supply is contracting versus still growing in the markets you are watching. The national trend is useful context; the local supply picture is what actually affects your returns.
Markets That Outperformed the National Benchmark
Santa Barbara, CA: Premium Coastal Holding Its Ground
StaySTRA data shows Santa Barbara at 67.1% occupancy in August 2026, down just 0.2 percentage points from 67.3% a year earlier. Paired with an average daily rate of $518 (up 7.6% from $481 a year ago), RevPAR for the market came in at approximately $347. Average monthly operator revenue was $9,549. The StaySTRA market score stands at 87.8 out of 100, the highest of any market in this report.
What keeps Santa Barbara outperforming is what has always kept it outperforming: supply is constrained by geography and regulation (3,188 active listings as of August 2026), and the guest profile skews toward higher-income travelers who book based on experience quality rather than price comparison. When you can raise rates 7.6% without moving the occupancy needle more than 0.2 percentage points, you are operating in a market with genuine pricing power. That is not common. The full Santa Barbara market data, including seasonality and listing trends, is on the StaySTRA location page.
Austin, TX: The Urban Outlier
Here is a number that stood out when I pulled it from the database: Austin occupancy reached 58.9% in August 2026, up 3.5 percentage points from 55.4% a year earlier. Every other major urban market in the StaySTRA dataset showed flat or declining occupancy for the same period. Austin was the outlier in the best possible way.
The caveat is that ADR dipped 4.7% to $199 (from $209 a year ago), so RevPAR came in at approximately $117. That is lower than the other outperforming markets in this report, but the occupancy trajectory points in the right direction for investors evaluating market entry timing. Average monthly operator revenue was $3,353 in August 2026, with 24,604 active listings. The StaySTRA market score stands at 56.5, reflecting Austin’s ongoing regulatory complexity alongside its strong demand fundamentals.
The occupancy gain is the signal to focus on. The ADR dip is a short-term softening that frequently precedes a pricing recovery once occupancy stabilizes at a higher level. Austin’s summer 2026 occupancy trajectory is the kind of leading indicator that shows up in the data before the revenue numbers fully reflect it. Check the Austin market page for the full data picture before drawing conclusions on entry timing.
Traverse City, MI: Lake Markets Delivering for Summer
Traverse City represents the lake market category in this report, and the August 2026 numbers justify the attention. Occupancy was 68.9%, down 1.4 percentage points from 70.3% a year ago, and still the highest rate of any market in this dataset. ADR rose 4.9% to $461 (from $440). RevPAR came in at approximately $318, and average monthly operator revenue was $8,569.
The 1.4-point occupancy decline, paired with a 4.9% ADR increase, tells you that Traverse City operators chose rate discipline over volume maximization during peak summer season. That is a healthy market behavior. Markets where operators discount to maintain occupancy end up in a race to the bottom that compresses returns for everyone. The StaySTRA market score of 59.6 reflects balanced fundamentals, with 5,178 active listings in a market with genuine four-season demand. The Traverse City location page has the complete data and seasonality picture.
Charleston, SC: Coastal Quality Holding Premium
Charleston came in at 63.6% occupancy (down 0.5 percentage points from 64.1% a year ago) with an ADR of $484, up 3.8% from $466 a year ago. RevPAR was approximately $308. Average monthly operator revenue was $8,745, making it the second-highest revenue market in this report behind Santa Barbara. The 11,850 active listings represent a mid-size competitive pool, and the StaySTRA market score of 75.3 reflects strong investability fundamentals.
The pattern here mirrors Santa Barbara: a small occupancy dip absorbed by meaningful rate growth, producing higher per-operator revenue than the prior year. That is how premium coastal markets are supposed to behave under supply pressure, and Charleston is executing it correctly. Charleston’s full market profile is on the location page.
Markets That Underperformed, and Why That Distinction Matters
Breckenridge, CO: Summer Softness in a Ski Market
Breckenridge is a challenging market to read in August. Occupancy came in at 47.7%, down 5.7 percentage points from 53.4% a year ago. ADR slipped 1.5% to $398 (from $404). Average monthly operator revenue was $5,272. StaySTRA market score stands at 46.5, reflecting the seasonal concentration of returns in ski season.
The context that matters: Breckenridge’s investment case is built almost entirely on winter. Summer is when occupancy is softest and when operators compete for a smaller demand pool. Both occupancy and rate declining in August is not unusual for a ski resort market, but it is a signal that the summer shoulder has not developed the demand depth that would create a year-round income cushion. The 4,781 active listings will face very different demand dynamics once ski season opens. The Breckenridge market data is worth studying alongside the seasonal occupancy curves before reading too much into a single summer month.
Park City, UT: Rate Discipline in a Ski Shoulder
Park City followed a different pattern from Breckenridge. Occupancy came in at 39.3%, down 3.7 percentage points from 43.0% a year ago. But ADR rose 9.5% to $451 (from $412). RevPAR came in at approximately $178. Average monthly operator revenue was $4,724. StaySTRA market score stands at 40.1. The 6,371 active listings face the same winter-driven demand dynamics as other mountain resort markets.
That 9.5% ADR gain during the summer shoulder is the signal worth noting. Think of it like a landlord raising rents during a soft leasing period: it signals confidence that winter demand will support the higher rate floor when it arrives. Park City operators absorbed a 3.7-point occupancy dip and came out ahead on pricing. The Park City location page shows the full seasonal occupancy curve, which is the right context for a single month’s performance.
Myrtle Beach, SC: Coastal Soft, Worth Watching
Myrtle Beach showed the most concerning Q3 data of any coastal market in this report. Occupancy came in at 59.5% in August 2026, down 5.0 percentage points from 64.5% a year ago. ADR rose 2.2% to $308 (from $301), which partially offset the volume decline. RevPAR was approximately $183. Average monthly operator revenue was $5,284. StaySTRA market score stands at 52.2 with 25,827 active listings.
The occupancy decline at Myrtle Beach is worth flagging because the ADR growth did not fully compensate for it. Unlike Santa Barbara or Charleston, where operators absorbed a modest occupancy dip and came out ahead on revenue, Myrtle Beach saw a large enough occupancy drop that the modest ADR gain only partially covered the gap. That pattern, when it persists across multiple quarters, can indicate a supply-demand imbalance that needs watching. The large listing pool (25,827) suggests supply competition remains a meaningful factor in that market. Check the Myrtle Beach market data and the supply trend detail before making entry or exit decisions.
Nashville, TN: The Market That Is Finding Its Level
Nashville showed 55.1% occupancy in August 2026, down 1.2 percentage points from 56.3% a year ago. ADR moved up slightly to $299, a modest 0.5% gain from $298 the prior year. RevPAR came in at approximately $165. Average monthly operator revenue was $4,765. StaySTRA market score stands at 80.6, the second-highest in this dataset, reflecting Nashville’s strong rental demand and investability fundamentals even as the near-term revenue metrics show some softness.
The gap between Nashville’s market score (80.6) and its near-term revenue trajectory tells a story experienced STR investors will recognize. Nashville remains a high-conviction long-term market that is working through a short-term inventory digestion period. Occupancy down 1.2 points with ADR essentially flat is not a crisis; it is a market finding its clearing level after a period of rapid supply growth. The 15,606 active listings represent a significant competitive pool, and the resolution of that supply dynamic will determine when Nashville’s revenue numbers re-accelerate. The Nashville market data has the full supply and demand picture.
Reading the ADR-Occupancy Pattern
If you lay all eight markets side by side, the pattern is cleaner than the individual headlines suggest. Think of it this way: occupancy and ADR are two sides of a pricing equation, and the markets that performed well in Q3 2026 are the ones where ADR grew faster than occupancy fell. Santa Barbara, Charleston, and Traverse City all fit that description. The markets that underperformed are the ones where the volume decline was too large for ADR gains to offset, or where rates could not hold their own.
That pattern is a direct consequence of supply dynamics. Think of it like the difference between a farmer’s market with three tomato vendors versus one: the single vendor does not need to cut prices. When fewer new listings compete for the same demand pool, operators can hold rates. When supply keeps growing, operators compete on price and the ADR line softens. The Q3 2026 data is consistent with what the industry supply data has been signaling for the past two quarters: the new listing pipeline is thinning, and operators who are already in market are holding more pricing power than they have in several years.
For investors watching the snowbird-season opportunity in the Sun Belt markets, the companion analysis at Best STR Markets for Snowbird Investors in 2026 is worth reading alongside this Q3 data. And for the broader 2026 market picture, the StaySTRA 2026 market overview adds supply-side context that quarterly data alone cannot provide.
Q4 2026 Outlook: What the Observable Data Direction Shows
I want to be careful here about what a Q4 outlook can honestly claim based on available data. There are no revenue projections below and no occupancy forecasts for November. What the data does show is the direction each market type is moving heading into Q4, and that direction is meaningful for investors who need to make positioning decisions now.
Mountain resort markets are set up for a reversal. Park City’s 9.5% ADR growth during the summer shoulder signals operator confidence in their pricing position as ski season approaches. Breckenridge’s summer softness reflects a market that has not developed strong year-round demand, but ski season bookings will tell the Q4 story. The occupancy declines that defined Q3 for these markets are structurally expected to reverse as winter demand arrives.
Premium coastal markets are sustaining rate discipline. Santa Barbara and Charleston both absorbed modest occupancy softness while protecting ADR through their strongest seasonal period. That behavior in Q3 suggests those operators will hold rates through the fall shoulder rather than discount. The Q4 outlook for premium coastal is steady-to-improving on RevPAR even as raw occupancy declines seasonally.
Urban markets are diverging. Austin’s positive occupancy trajectory is the clearest Q4 leading indicator in this dataset. Nashville’s soft-but-stable picture suggests a market that is neither deteriorating nor recovering quickly. For urban market investors, the Q4 watchpoint is whether Austin’s occupancy gains translate into ADR recovery, and whether Nashville’s modest ADR growth holds or stalls under continued supply pressure.
Supply tightening continues to favor established operators. The slowdown in new listing growth is not evenly distributed, but the overall direction is toward a less competitive supply environment than 2023 or 2024. That is a structural tailwind for investors who are already in market with established listings, review histories, and operational track records. New entrants face a harder competitive environment than the raw demand numbers might suggest.
If you want to understand how your specific market compares against this Q3 picture and whether the data direction suggests entry or hold, the StaySTRA Analyzer gives you the market-level occupancy, ADR, and RevPAR benchmarks for every city in the database.
Frequently Asked Questions
What was the average STR occupancy rate nationally in Q3 2026?
Industry data from AirDNA’s 2026 midyear report projects national STR occupancy averaging around 57.4% for 2026, edging above the pre-pandemic benchmark of approximately 57.0% (AirDNA). Individual markets varied significantly: StaySTRA data shows Q3 2026 occupancy ranging from 39.3% in mountain resort shoulder markets like Park City to 68.9% in peak summer lake markets like Traverse City. Urban markets typically sat in the 55-60% range, and premium coastal destinations held near 63-67%.
Which STR markets had the best performance data in Q3 2026?
The strongest Q3 2026 performers in the StaySTRA dataset were markets where ADR growth outpaced any occupancy softness. Santa Barbara showed only a 0.2-point occupancy decline with 7.6% ADR growth and averaged $9,549 per month. Charleston posted a 0.5-point occupancy dip alongside 3.8% ADR gains and $8,745 per month. Traverse City held 68.9% occupancy with 4.9% ADR growth and $8,569 per month. Austin was the notable urban outperformer with occupancy up 3.5 percentage points year-over-year.
Why did mountain STR market occupancy decline in Q3 2026?
Mountain resort markets like Breckenridge and Park City typically see lower summer occupancy than winter because their primary demand driver is ski season, which runs roughly November through March. Comparing August 2026 to August 2025 is an apples-to-apples seasonal comparison, so a year-over-year summer decline signals softer demand, not just seasonality. For investors evaluating mountain markets, the ski-season occupancy curve is the more meaningful benchmark than summer data alone.
What does STR supply data show heading into Q4 2026?
New listing growth has slowed significantly relative to the 2023-2024 pace. That supply tightening means established operators face less direct competition for bookings entering Q4, which is a structural support for both occupancy rates and ADR. Markets with the largest existing listing pools (Myrtle Beach with 25,827, Austin with 24,604, Nashville with 15,606) still face meaningful internal competition, but the overall supply direction favors operators who are already in market over new entrants.
How do I benchmark my STR performance against Q3 2026 market data?
Compare your property’s Q3 occupancy rate to the market average for your specific city, not the national figure. A 55% occupancy rate in Nashville is right at the market average; the same rate in Traverse City during summer would be significantly below the 68.9% local benchmark. RevPAR benchmarking is even more useful than occupancy alone because it captures both rate and volume simultaneously. The StaySTRA Analyzer gives you the market-level occupancy, ADR, and RevPAR benchmarks for your specific location so you can evaluate your property against the local market.
What is RevPAR and why does it matter more than occupancy alone for STR investors?
RevPAR, or Revenue Per Available Room, is calculated by multiplying occupancy rate by average daily rate. A market at 68% occupancy and $200 ADR has a RevPAR of $136. A market at 55% occupancy and $300 ADR has a RevPAR of $165. The second market is generating more revenue per available night despite lower occupancy. RevPAR gives investors a single comparable number that captures both dimensions of performance simultaneously. In Q3 2026, RevPAR told a more complete story than occupancy alone in every market featured in this analysis.
The Q3 2026 data confirms the direction that supply and demand signals have been pointing toward for most of 2026: the market correction of 2023-2024 has worked through the system, established operators in premium markets are holding pricing power, and the markets that reward disciplined rate management are producing results. The question for investors is not whether the broad picture is positive. The question is whether the specific market you are watching is executing the ADR discipline that makes Q3 momentum carry into Q4.
Run your market through the StaySTRA Analyzer to see occupancy, ADR, and RevPAR benchmarks for your target city and compare against what Q3 2026 showed for similar market types.
Become a StaySTRA Insider
Join free — get our newsletter + 1 free property analysis/month.
No spam. Unsubscribe anytime. Free membership includes property analyses and market insights.
We do our best to keep our data accurate and up to date, but markets move fast and we are only human. Always verify current figures directly with local sources before making investment decisions. StaySTRA market metrics in this article are compiled through August 2026; September 2026 data is being finalized.